The Daily Brief
TSMC end of day: record $23.9B profit, 69% surge — stock falls 1.8% anyway
Revenue hit $46.7B (+41% YoY), beating guidance, as AI demand once again exceeded supply. Q4 guide of $52.3–54.3B topped consensus. The market sold it anyway.
What happened#
Taiwan Semiconductor — the world's largest dedicated chip foundry, the company that manufactures the silicon inside Nvidia's AI accelerators, Apple's iPhones, and AMD's data-center chips — reported third-quarter results this morning that beat on every line. By the closing bell, the stock had fallen 1.8% to $422.15.
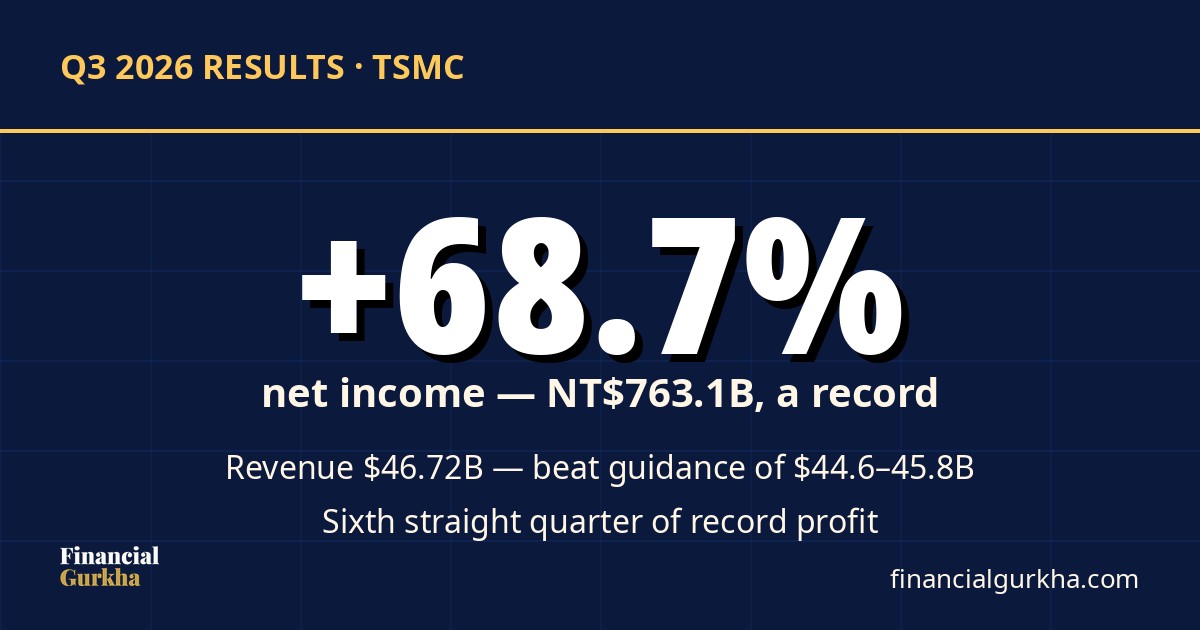
| Metric | Q3 2026 | Change |
|---|---|---|
| Revenue | NT$1,494.2B ($46.72B) | +50.9% YoY / +17.6% QoQ |
| Net income | NT$763.1B ($23.9B) | +68.7% YoY — a record |
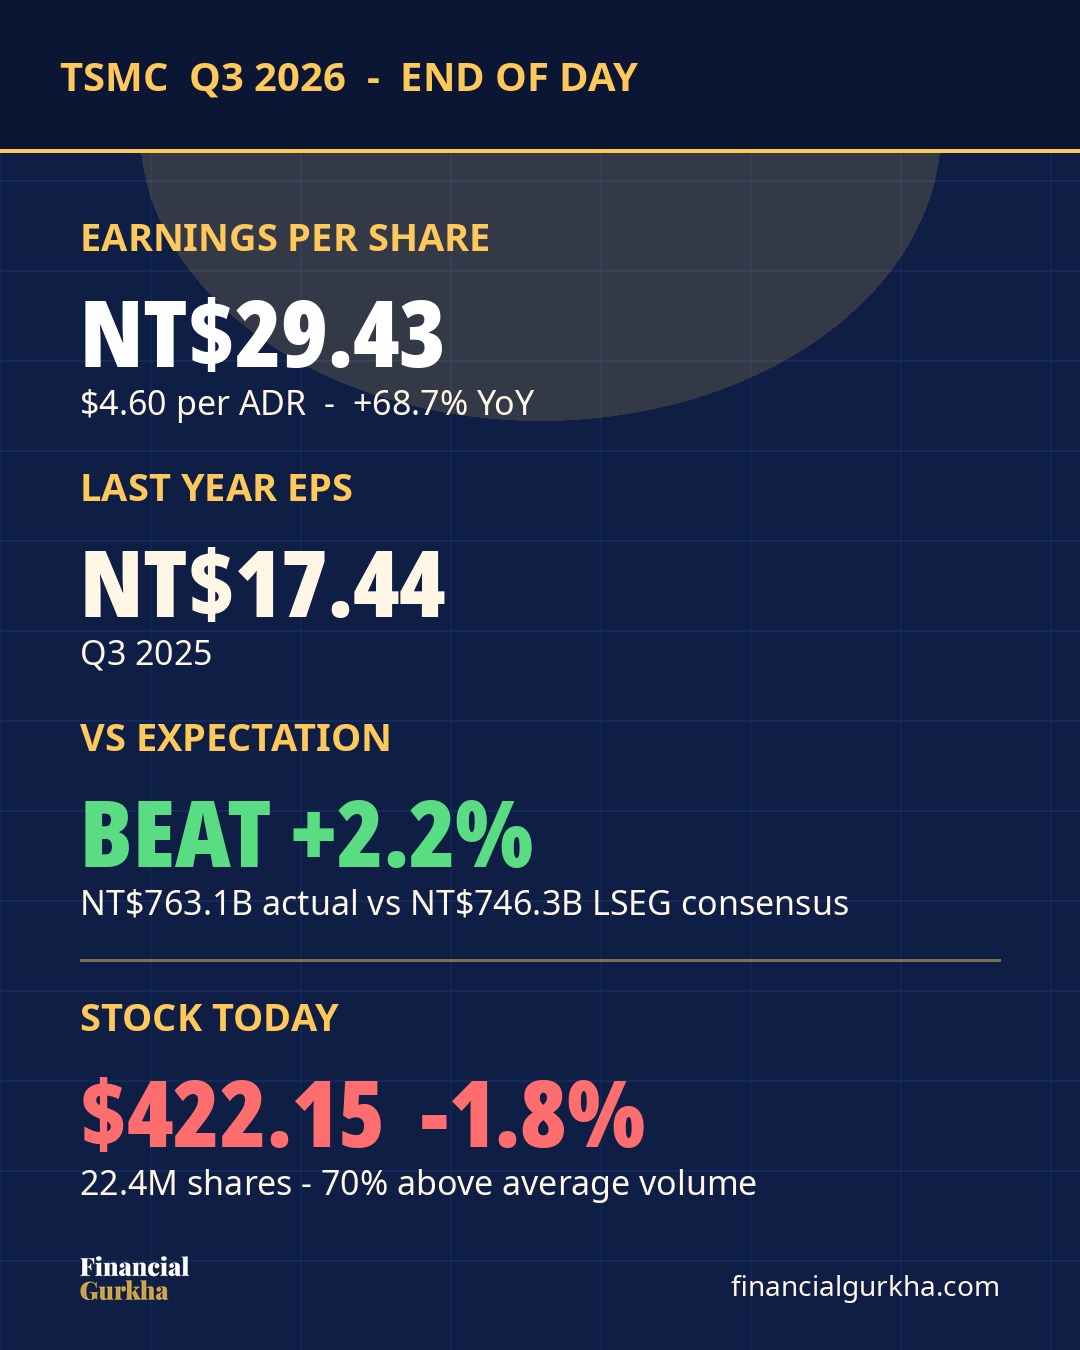
| Diluted EPS | NT$29.43 ($4.60/ADR) | +68.7% YoY (vs NT$17.44) |
| vs consensus | NT$763.1B actual vs NT$746.3B (LSEG) | +2.2% beat |
| Gross margin | 66.4% | vs 59.5% a year ago |
| Operating margin | 58.7% | — |
| Net margin | 51.1% | — |
Revenue beat the company's own guidance ($44.6–45.8B). It was the sixth straight quarter of record profit.
The number behind the number#
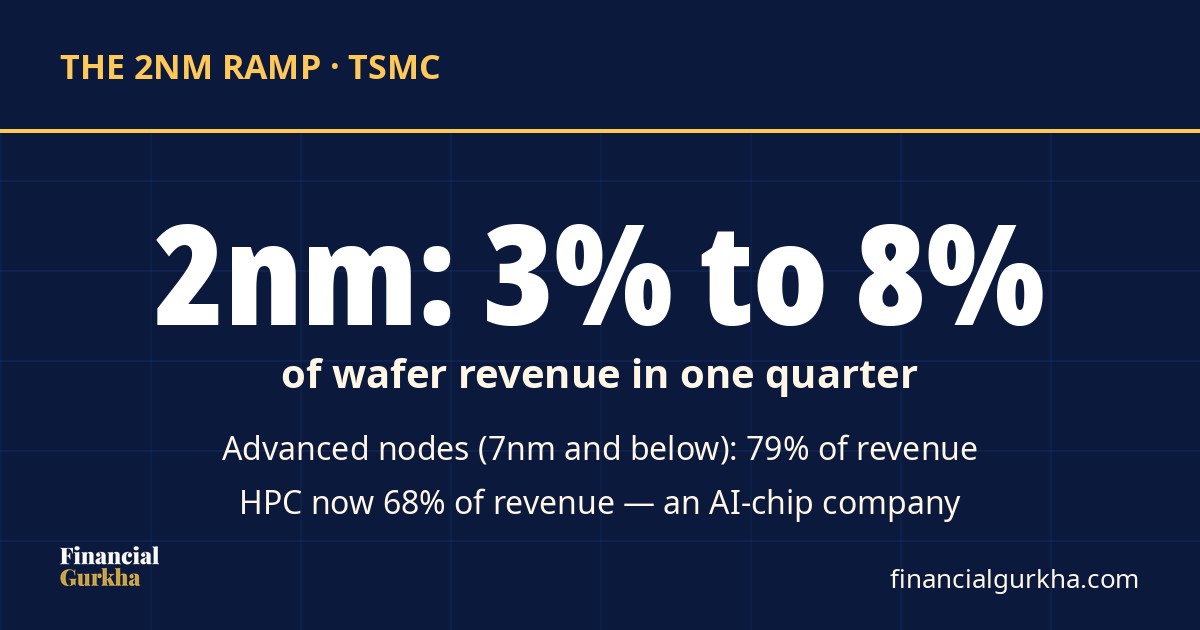
Two details matter more than the headline. First, the 2-nanometer ramp: the newest node jumped from 3% of wafer revenue in Q2 to 8% in Q3, with 3nm at 33% and 5nm at 28% — advanced nodes (7nm and below) now account for 79% of wafer revenue. Second, high-performance computing hit 68% of total revenue, up from 57% a year earlier, while smartphones shrank to 21%. TSMC is no longer a phone-chip company that does AI on the side. It's an AI-chip company.
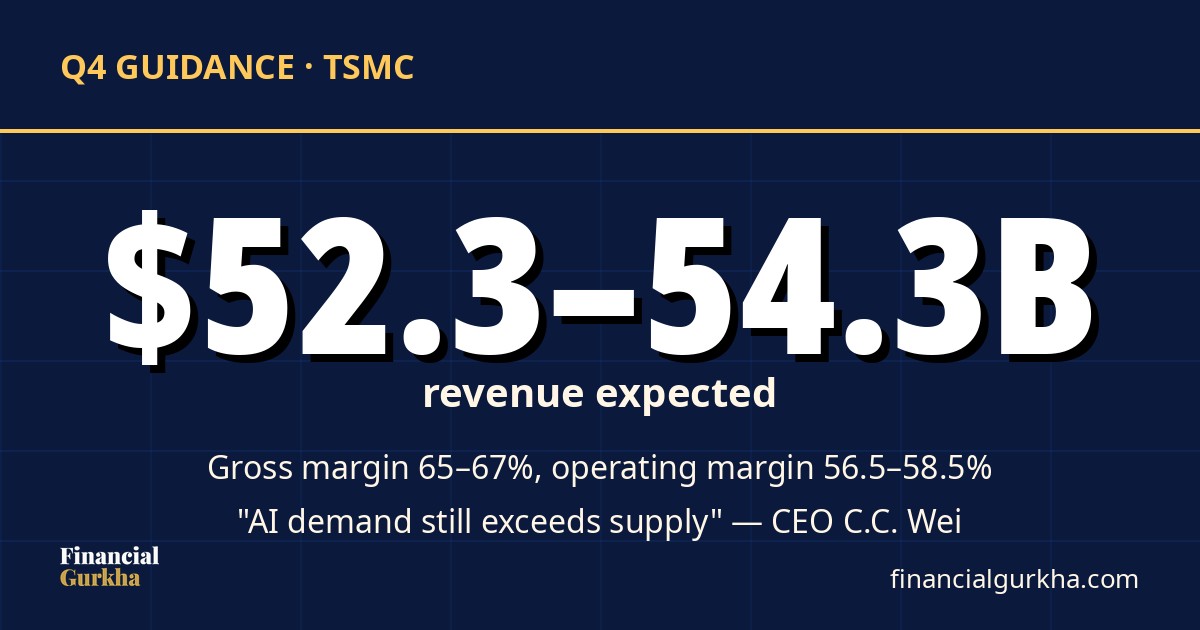
CEO C.C. Wei's line from the call says it all: AI demand still exceeds TSMC's supply capability. The company is working to narrow the gap and is reportedly evaluating expansion beyond Arizona, including Texas.
For Q4, management guided revenue of $52.3–54.3B — comfortably above the roughly $48.8B consensus — with gross margins of 65–67%, supported by the steep 2nm ramp.
The closing bell#
TSM closed at $422.15, down 1.8% from $430.00, on 22.4M shares — about 70% above average volume. Intraday range: $407.13–$423.66. The stock sits ~13% below its $487.47 all-time high from October 5, with a market cap around $2.2T. For context, the shares are still up ~39% year-to-date.
Wall Street isn't blinking: Needham raised its price target from $530 to $560 today and kept a Buy rating, citing long-term AI growth.
Our take#
This is the foundry pulse of the entire AI trade: when the company that makes everyone else's chips says demand exceeds supply for the sixth straight record quarter, the AI capex cycle is not over — whatever the Nasdaq did today. The selloff looks like classic "priced for perfection" profit-taking on a day the whole tech complex was shaky, not a fundamental crack.
One valuation note: with the 10-year Treasury at ~5.06% and the Fed funds rate at 3.75–4%, the discount rate on future cash flows is doing real work against even great earnings. TSMC's margins (66% gross, 51% net) are the envy of manufacturing — but at these rates, the market demands the growth be not just real, but perpetual. Today's reaction suggests it's starting to ask whether it is.
This is a news summary, not financial advice. Nothing here is a recommendation to buy, sell, or hold anything.
Where this came from
Plain-English explainers, not advice. Nothing here tells you to buy, sell, or hold anything.