The Daily Brief
PPI roars 1.3% — biggest jump since March 2022 — and the October-hike thesis just gained fuel
Wholesale inflation hit 6.3% YoY on a gasoline surge (+20.3% in a single month), while retail sales beat at +0.8% headline — but only +0.2% once you strip out gas and autos.
What happened#
The last hard inflation data before the Fed's October 27–28 meeting landed this morning — and it was hot on both sides of the ledger.
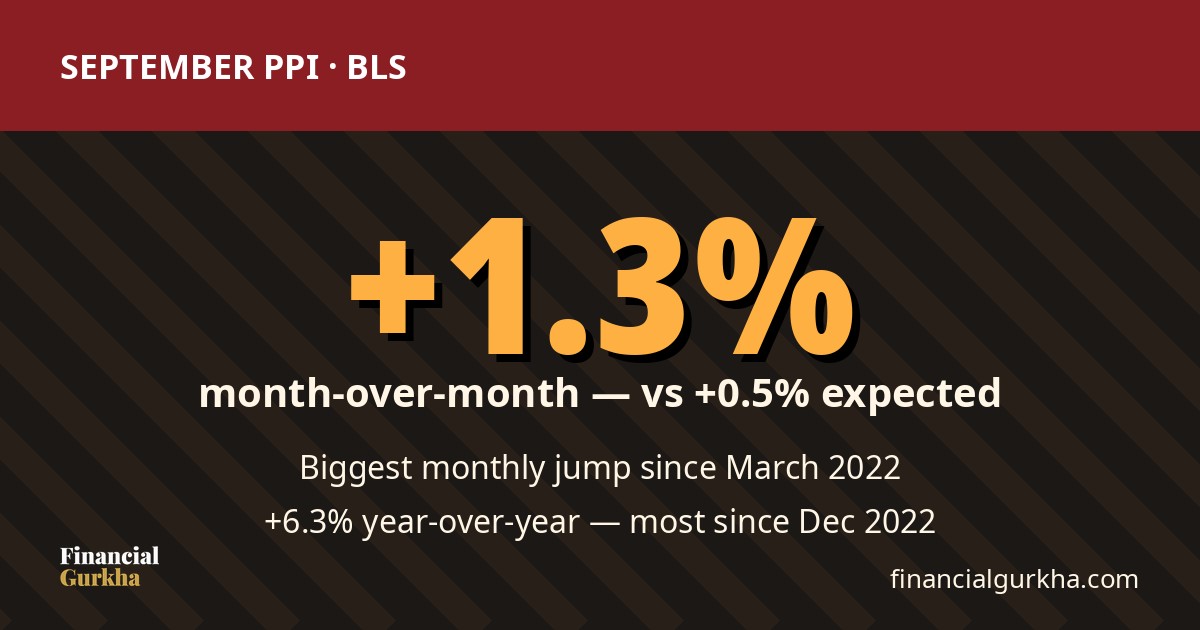
September PPI (BLS): The Producer Price Index for final demand jumped +1.3% month-over-month (vs +0.5% expected) — the largest monthly advance since March 2022. Year-over-year, wholesale inflation hit +6.3%, the biggest 12-month gain since December 2022. The core measure (less foods, energy, and trade services) ran warm too: +0.5% MoM / +5.0% YoY.
| Measure | Aug 2026 | Sep 2026 |
|---|---|---|
| Headline PPI (MoM) | +0.5% | +1.3% |
| Headline PPI (YoY) | 5.6% | +6.3% |
| Core PPI (MoM) | +0.3% | +0.5% |
| Core PPI (YoY) | 4.8% | +5.0% |
| Final demand energy (MoM) | +4.5% | +10.8% |
| Final demand goods (MoM) | +1.1% | +2.6% |
| Final demand services (MoM) | +0.2% | +0.8% |
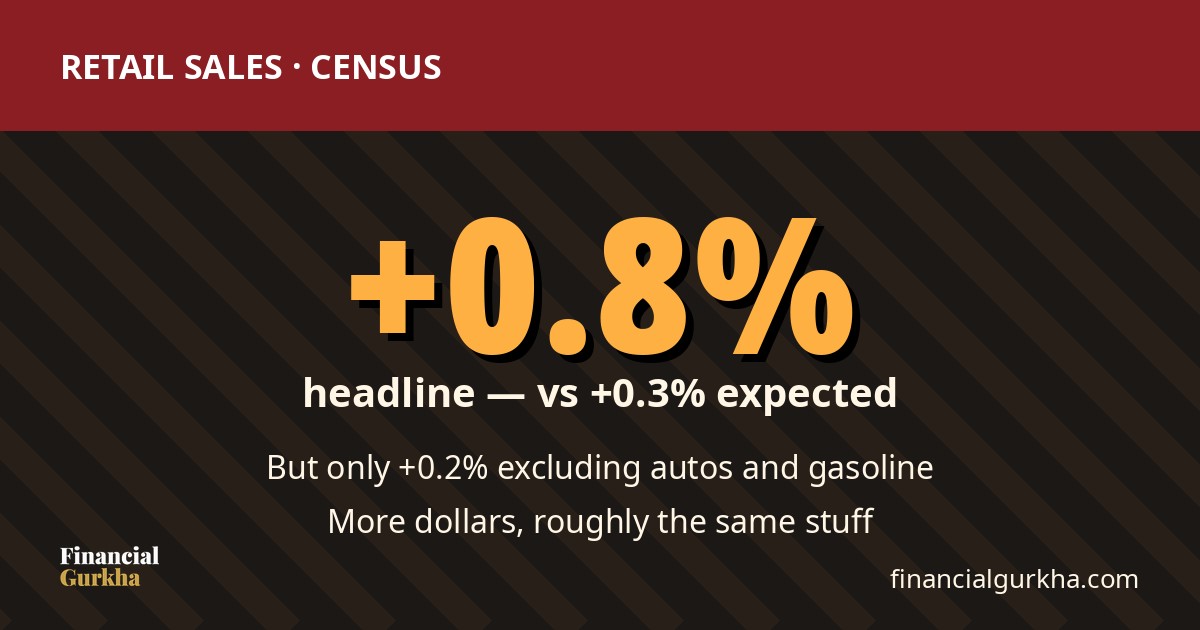
September retail sales (Census): Headline sales hit $745.0 billion, +0.8% MoM (vs +0.3% expected) — a real beat, with August revised up from +1.1% to +1.3%. But the composition tells the story: excluding autos, +0.9%; excluding autos and gasoline, just +0.2%. Gasoline stations' receipts jumped +6.4% MoM and +28.1% YoY as record pump prices turned into spending, not volumes. Remember: retail sales are not adjusted for price changes — the headline is part spending, part inflation.
The number behind the number#
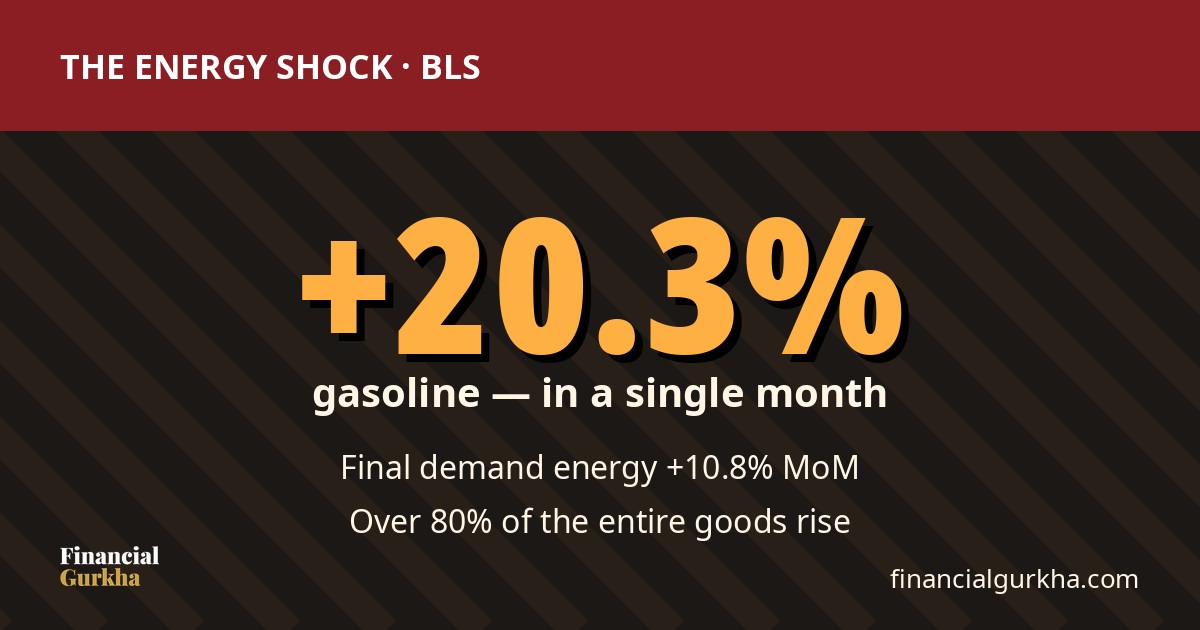
This was an energy shock wearing a wholesale-inflation costume. Final demand energy jumped 10.8% in a single month, accounting for over 80% of the broad-based goods rise. Gasoline alone spiked 20.3% — tracing to about half of the total goods gain on its own. Diesel, jet fuel, and crude petroleum all surged alongside it.
That confirms the core of our CPI-brief take: this inflation is energy-led — global conflict and supply disruption, not a broad demand spiral. The hoped-for "hot headline, calm core" combo failed twice running, though: CPI core ran warm at 2.6% yesterday, and now PPI core is +0.5% MoM / 5.0% YoY. Underlying pipeline pressure is real, not just pump prices.
On the consumer side, the retail beat is genuine but stretched: strip the gas-price windfall and underlying spending grew +0.2% — households paying more dollars for roughly the same stuff, exactly the squeeze the CPI brief described. People are prioritizing: everyday essentials and electronics held up, while deferrable big tickets (furniture −3.4% MoM) stalled.
Our take#
The Fed walks into its October 27–28 meeting with wholesale inflation at 6.3% YoY and September PCE not landing until October 29 — after the decision. This morning was effectively the last hard inflation data before that call, and it handed the October-hike thesis serious fuel.
Net: the energy diagnosis holds, but the "cooling in a month or two" call from our CPI brief now rests entirely on oil prices coming down — the pipeline data no longer offers any comfort of its own. Watch crude: if the Iran-driven spike eases, a large chunk of this unwinds. If it doesn't, the Fed has a problem no amount of patience solves.
This is a news summary, not financial advice. Nothing here is a recommendation to buy, sell, or hold anything.
Where this came from
Plain-English explainers, not advice. Nothing here tells you to buy, sell, or hold anything.